Copper Hits Record High Amid US Tariff Fears

Copper futures pushed to fresh all-time highs this week, with three-month contracts on the London Metal Exchange touching an intraday peak of $14,617 a tonne on September 8 — the second consecutive session at a record — as traders continued to bet on looming US import tariffs even as physical supply tightens.
The rally has been building for months. LME copper is up roughly 17% since the start of 2026, and Comex futures touched a record $6.71 a pound in August. According to Reuters, the advance is being driven by two forces pulling in the same direction: anticipation of a US tariff on refined copper, and a widening gap between mine output and demand from data centers, electric vehicles and grid upgrades.
What's driving the surge
Washington has kept refined copper exempt from tariffs even after imposing a 50% duty on semi-finished copper products last year, but the US Commerce Department was directed to report back on whether to extend tariffs to refined metal by June 30, 2026. That deadline has now passed by more than two months with no public decision from the White House, according to Yahoo Finance's review of the process. Reuters has reported that officials have discussed a phased rate — around 15% from January 2027, rising to 30% in 2028 — though nothing has been finalized.
The uncertainty itself has moved the market. Traders have shipped copper toward the US to get ahead of any tariff, pushing Comex inventories to 675,185 tonnes — 46 straight days of increases and a record level — while draining stock elsewhere: LME warehouses saw net withdrawals of 65,400 tonnes, and Shanghai Futures Exchange inventories fell to their lowest since 2024. US refined copper cathode imports reached 885,000 tonnes in the first half of 2026, up 3% year-on-year, after a record 1.64 million tonnes for all of 2025.
Why it matters
Underneath the tariff story sits a supply problem analysts say predates it. Copper has gained more than 68% since April 2025 — a run that started well before this year's tariff speculation, according to market analyst Jim Bianco. The International Energy Agency has separately warned that ore grades have declined roughly 40% since 1991, new mine lead times now run close to 17 years, and treatment and refining charges — the fee smelters earn to process ore into metal — collapsed to zero at the last annual benchmark, a sign that smelting capacity has outrun the concentrate available to feed it. On current project pipelines, the IEA estimates the market could face a supply deficit of 30% by 2035.
Global industry impact
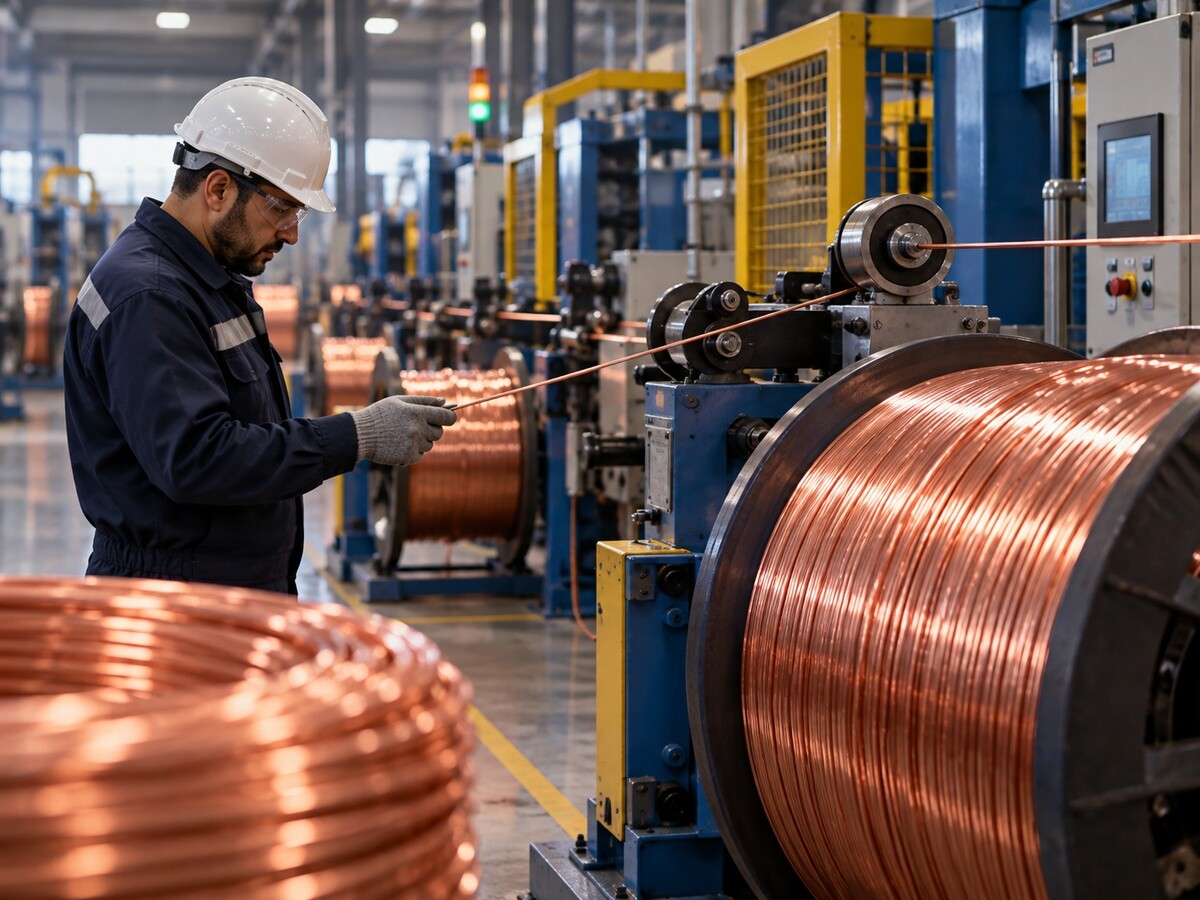
For manufacturers of cable, wiring, electrical equipment, HVAC systems and EV components, sustained record copper prices mean higher input costs that will eventually show up in quoted prices for finished goods. For mining companies and copper-exporting economies, the same rally is a windfall. Commodity strategists are split on where prices go next: Macquarie's Alice Fox has said a confirmed tariff could send prices "massively" higher, while Glencore chief executive Gary Nagle has argued that a final decision — whichever way it goes — could actually calm the market by removing the uncertainty traders are currently pricing in.
What to watch next
The key trigger is the overdue US Commerce Department decision on refined copper tariffs, which the White House has not yet made public. Also worth tracking: whether Comex inventory keeps climbing at the expense of LME and Shanghai stock, and whether major producers in Chile and Peru — where output has been declining — report any recovery. Global mined copper production is on track for its first annual decline since 2017, a trend that would keep the underlying supply deficit in place regardless of how the tariff question is resolved.
Sources
Bloomberg, Reuters (via Investing.com), Business Standard, Yahoo Finance, the International Energy Agency and Trading Economics.